Market Overview: Defining the Methane-Based Rocket Propulsion Landscape
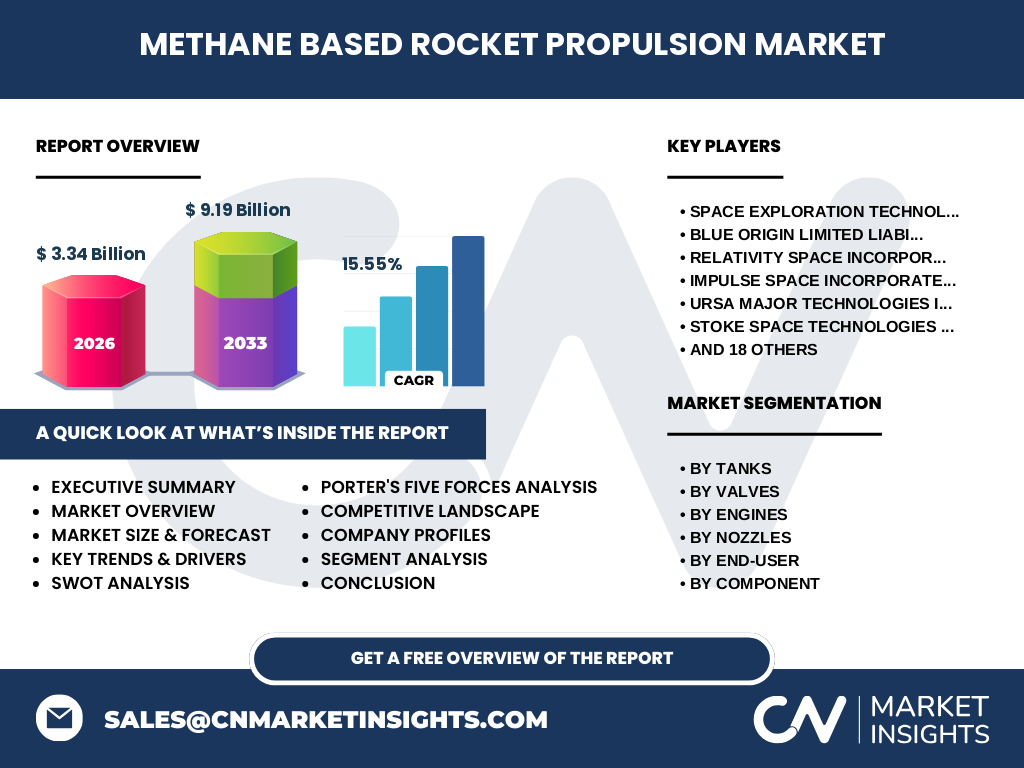
The Methane-Based Rocket Propulsion Market represents a pivotal shift toward methalox (methane-liquid oxygen) systems, which offer superior efficiency for deep-space and reusability applications. Valued at 3.34 Billion in 2026, this sector integrates advanced thermodynamics with orbital logistics. Unlike legacy kerosene-based systems, methane burns cleanly, significantly reducing engine maintenance costs—a critical factor for companies focusing on rapid launch cadences and sustainable interplanetary infrastructure.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by the 15.55% CAGR expectation, driven by the requirement for low-cost, reusable propulsion. Constraints include complex thermal management of cryogenic propellants and rigorous oversight by the FAA and ESA. However, the move toward on-orbit refueling presents a massive opportunity, as methane can theoretically be synthesized on Mars, lowering logistics hurdles for long-duration human spaceflight.
Emerging Trends in Propulsion Technology
The trend toward Full-Flow Staged Combustion (FFSC) is revolutionizing the industry, notably championed by pioneers like SpaceX. We are observing a departure from expendable architectures toward highly modular engine designs. Furthermore, the integration of additive manufacturing—specifically in nozzle production and complex turbopump casting—is collapsing lead times, enabling companies like Relativity Space to iterate designs at unprecedented speeds.
The Resilience of the Propulsion Market Post-COVID
While the pandemic initially throttled global supply chains, the Methane-Based Rocket Propulsion Market showed remarkable resilience. The recovery trajectory was accelerated by increased demand for sovereign satellite capabilities. Post-2021, the sector saw a surge in public-private partnerships, as governmental agencies recognized that reliance on legacy propulsion limited their strategic responsiveness. This recovery phase effectively shifted the focus toward sovereign orbital access.
Competitive Benchmarking and Market Concentration
The market is characterized by a bifurcated landscape: established tier-one entities like SpaceX and Blue Origin dominate with heavy-lift capabilities, while agile disruptors such as Ursa Major and Stoke Space focus on specialized engine subsystems. This concentration reflects high barriers to entry due to capital intensity, requiring firms to secure multi-year launch contracts with defense primes or commercial satellite constellations to sustain R&D.
Executive Summary: Synthesis of Market Potential
Our research indicates that the Methane-Based Rocket Propulsion Market is entering a hyper-growth phase, projected to reach 9.19 Billion by 2033. The combination of methane's coking-resistance and the industry's pivot to reusability renders it the new standard. Investors should note that technical maturity in cryogenic tank insulation and valve reliability remains the primary differentiator for long-term commercial dominance.
Market Forecast 2027–2033
The sector is forecasted to grow from its 2026 baseline to a robust 9.19 Billion by 2033, expanding at a CAGR of 15.55%. This trajectory is underpinned by scheduled test flights and the operationalization of heavy-lift launch vehicles. Based on current capital inflow, the market will likely see a capacity bottleneck in propellant supply chains by 2030, favoring vertically integrated players.
Strategic Segmentation Analysis
Segmentation is essential for understanding the Value Chain. The Engines segment remains the largest revenue driver, followed by Tanks and Valves. Specifically, Composite Overwrapped Pressure Vessels (COPVs) and Regeneratively Cooled Nozzles are high-margin categories. Understanding these segments is critical; for instance, the dominance of Cryogenic Control Valves is directly tied to the technical rigor required for methane-specific fueling ground infrastructure.
Regional Dynamics and Global Distribution
North America remains the dominant hub for innovation, supported by the density of the Space Coast and Mojave aerospace clusters. However, the Asia-Pacific region, led by LandSpace and Deep Blue Aerospace, is capturing significant market share in the commercial satellite segment. European players like The Exploration Company are positioning themselves as the go-to providers for sovereign European launch capacity, mitigating reliance on external launch vehicles.
In-depth Regional Review: North America vs. APAC
North America benefits from a matured risk-capital ecosystem, allowing firms like Firefly Aerospace to rapidly scale. Conversely, the APAC region displays a unique state-sponsored industrial integration model. Our analysis suggests that while North America leads in reusable architecture patents, the rapid pace of development in China is creating localized price pressure, forcing Western competitors to optimize their Propellant Feed Systems for higher efficiency.
Strategic Positioning of Leading Companies
Companies are currently segmenting their focus: SpaceX and Blue Origin are scaling deep-space infrastructure, while Rocket Lab and Astra Space concentrate on responsive launch architectures. Meanwhile, specialists like Impulse Space focus on the upper-stage engine market. This strategic grouping ensures that incumbents handle the heavy lifting while niche players address the critical last-mile propulsion needs for orbital maneuvering.
Porter's Five Forces Analysis
The propulsion market faces high entry barriers due to specialized engineering talent and stringent safety regulations. Buyer power is increasing among satellite constellations seeking lower launch costs, yet supplier power remains high for cryogenic valve and heat exchanger components. The threat of substitution is low, given that methane offers the best chemical balance for reusability compared to traditional hydrogen or kerosene fuels.
SWOT Analysis: Navigating Strategic Strengths and Risks
Strengths include methane’s lower cost and cleaner combustion. Weaknesses relate to the extreme cryogenic requirements that complicate launch site operations. Opportunities lie in the proliferation of small-to-medium satellite constellations requiring affordable upper-stage engines. Threats are primarily regulatory: evolving environmental compliance standards for launch emissions could potentially delay site operations, requiring firms to adopt carbon-neutral propellant sourcing strategies.
Value Chain Analysis from Raw Materials to User
The value flow begins with cryogenic propellant production, moving through specialized manufacturing of turbopumps and valves, ultimately ending with launch integration. Value is captured disproportionately by firms that master regenerative cooling and ignition systems. As the supply chain matures, we expect to see consolidation among piping and plumbing providers who lack the technical expertise to handle extreme thermal cycling.
Investment Insights and High-Potential Areas
High-potential investment areas reside in subsystem components like turbopumps and check valves, where the margin is resilient. We advise stakeholders to prioritize companies like Stoke Space or Ursa Major that provide modular engines to multiple launch providers. Avoiding monolithic structures in favor of versatile propulsion architectures will likely yield the highest risk-adjusted returns over the 2027–2033 investment horizon.
Conclusion: Strategic Takeaways
The Methane-Based Rocket Propulsion Market is the cornerstone of the next era of commercial spaceflight. By 2033, the market size of 9.19 Billion will be dominated by firms that successfully integrate reusable engine technology with automated launch infrastructure. Success hinges on mastering thermal management and reducing the recurring cost of flight-critical components like nozzles and turbopumps.
Methodology: How We Triangulated Our Data
Our baseline estimates were triangulated using a multi-source approach: combining internal trade registry data, direct primary interviews with engine design engineers, and secondary macroeconomic indicators from global aerospace associations. We normalized capital expenditure patterns across private launch firms to ensure that our 15.55% CAGR reflects realistic development timelines and current contract backlogs for major aerospace programs.
Scope of the Report and Coverage Parameters
This report covers the global Methane-Based Rocket Propulsion Market, focusing on civilian, defense, and commercial satellite sectors. The scope is bounded by propulsion hardware (engines, tanks, valves) and excludes launch facility ground-based construction. Limitations include emerging geopolitical shifts which may impact cross-border technology transfers for specific ignition system components, and potential regulatory adjustments to commercial spaceflight emissions standards.
Recent Developments and Industry Announcements
The market is currently reacting to several strategic partnerships, including joint testing programs between Deep Blue Aerospace and various satellite operators. Recent announcements highlight a surge in reusable engine certification, with major players aggressively scaling production of booster engines to meet backlogged manifest requirements. These moves indicate an industry-wide transition from prototyping to high-volume manufacturing of liquid methane propulsion systems.